 Kenal
Kenal Loan
Originate and manage any loan, conventional or Islamic, in one system.
Borrowers apply, sign and repay on their phone. Your team decides, pays out, services, collects and reports from one console, on one ledger, and no money moves until every check has passed.
Last updated
What Kenal Loan is
Kenal Loan is a loan origination and loan management system for conventional loans and Islamic financing, including Tawarruq and Murabahah, with market packs for Malaysia and Indonesia.
It covers the whole life of a loan, from the first application to the day the account closes. Each country's rules come from a market pack, so the same system serves a Malaysian moneylender and an Indonesian multifinance company.
- Loan types
- Any loan type: personal, device, hire purchase, working capital and asset-backed credit.
- Islamic financing
- Tawarruq and Murabahah, next to conventional loans.
- Markets
- Market packs for Malaysia and Indonesia.
- Channels
- Borrower app, officer counter and dealer network.
How it works
Nine steps take a loan from application to settlement. Conventional loans and Islamic financing follow the same path.
Apply
In the borrower app, or at the counter with an officer.
Verify
Identity, liveness, and AML, PEP and sanctions screening.
Decide
Your credit policy, affordability and eligibility rules.
Sign
The agreement for the loan's mode, signed in the app.
Stamp
Stamp duty computed from the agreement terms.
Disburse
Paid out only through the funding gate.
Service
Schedules, daily accrual and payments to the sen.
Collect
Cases by days past due, reminders and promises to pay.
Settle
Settlement with rebate or ibra', and a closed account.
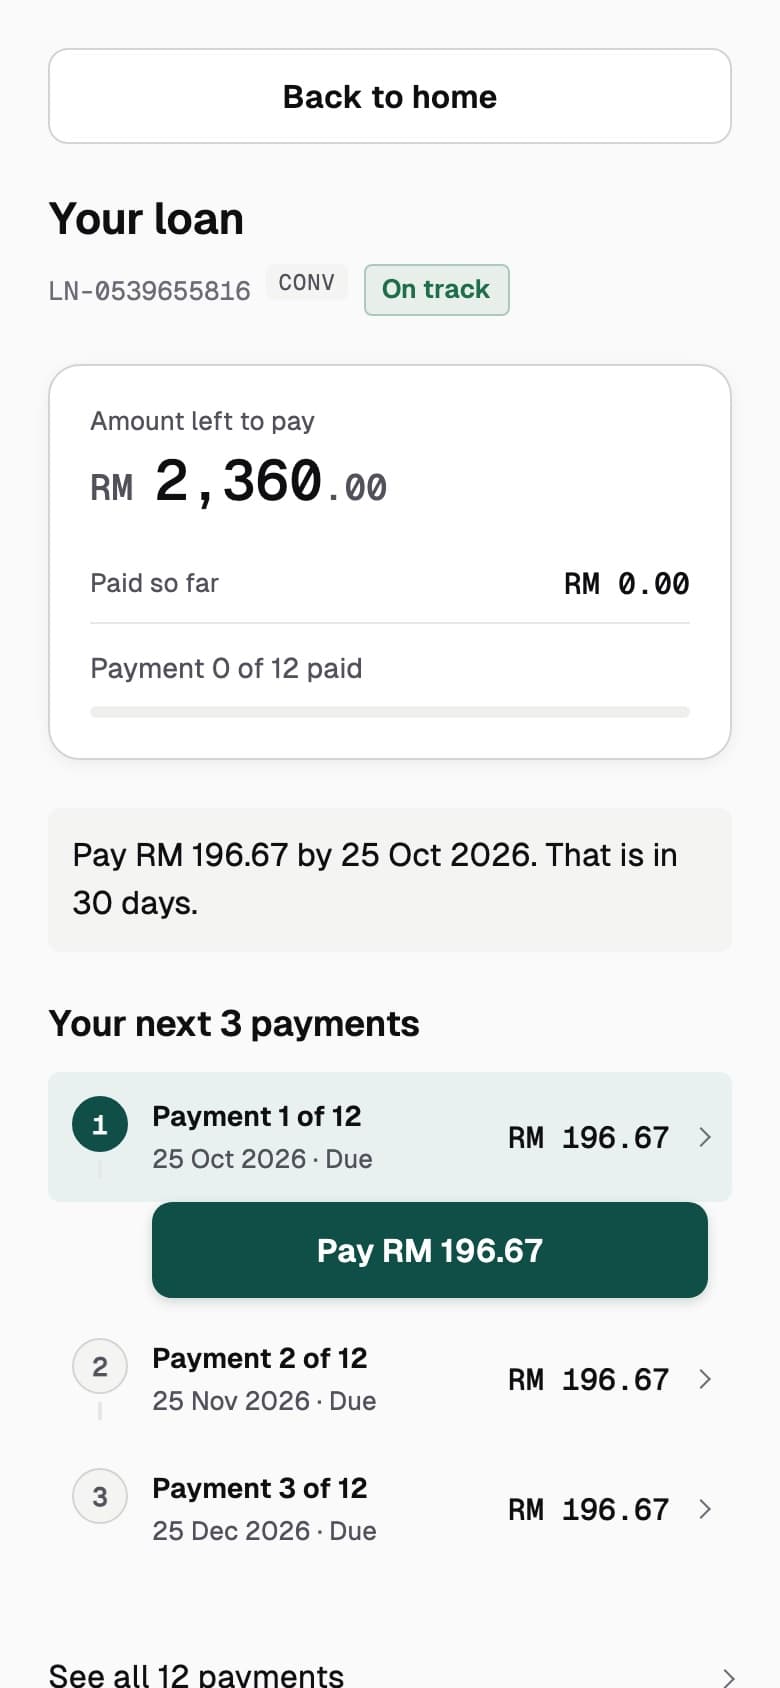
The borrower applies and sees the cost up front
Borrowers apply on their phone, or an officer applies for them at the counter. The monthly payment and total cost are shown in plain language before anything is signed, and the credit decision comes first, so a clear decline costs no identity checks or document reviews.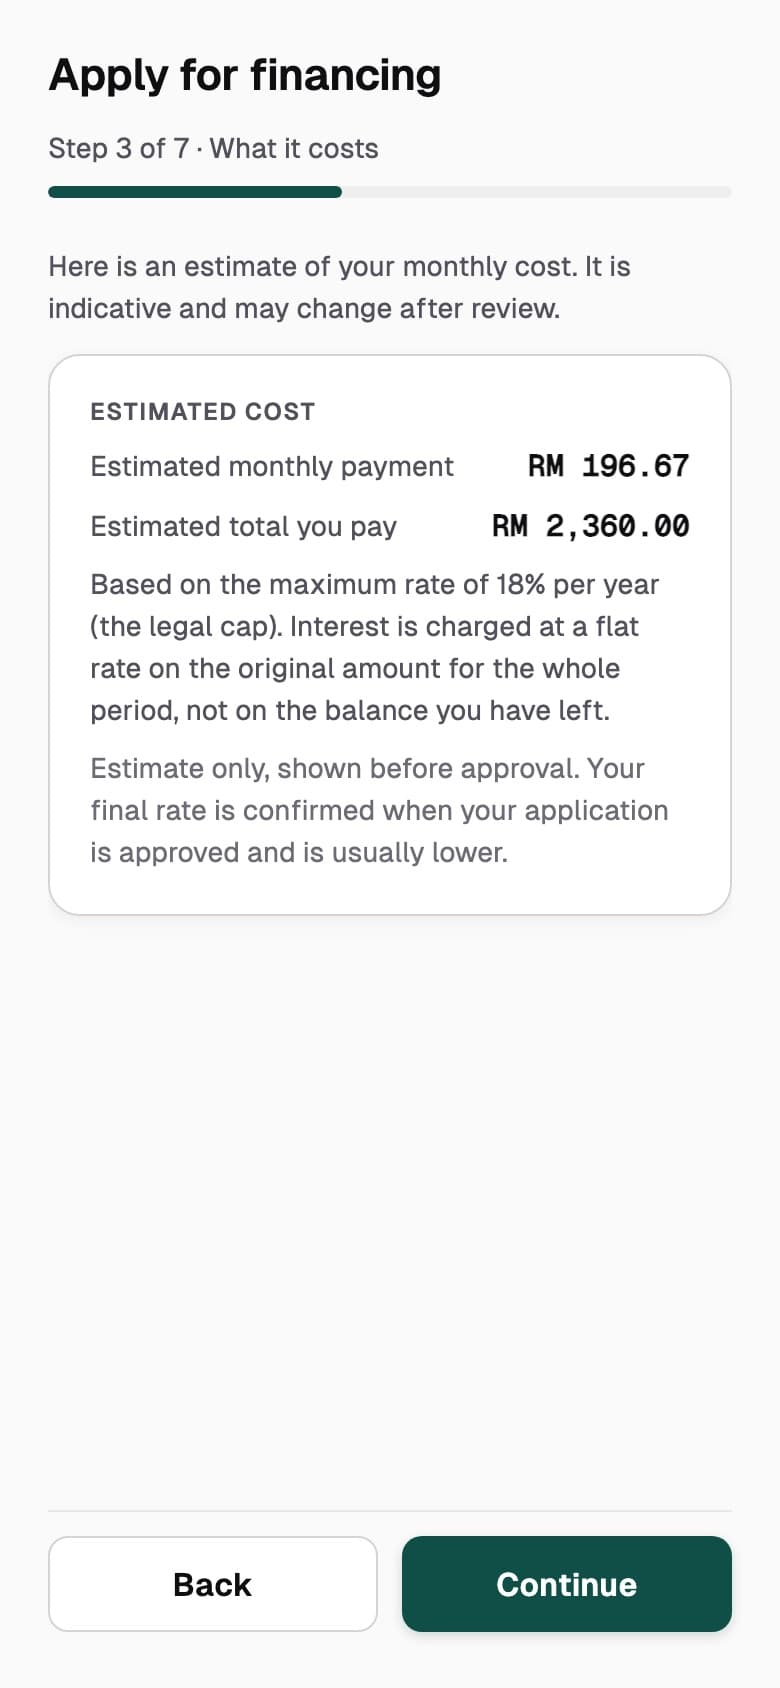
Your credit policy decides, and officers take the referrals
Score bands, arrears rules, affordability and eligibility decide each application under the policy you set. Clear cases are approved or declined automatically. Borderline ones go to an officer's queue with the evidence beside them.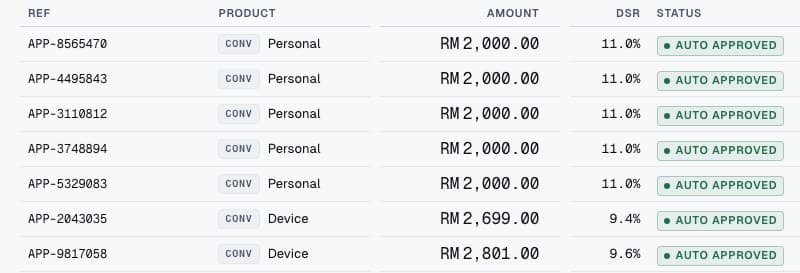
Sign, stamp and pay out, with the proof on file
The agreement is generated for the loan's mode and signed in the app. Stamp duty is computed from the agreement terms. Every stage and check sits on one timeline with the decision proof, so anyone can see why a loan was approved and when it was paid.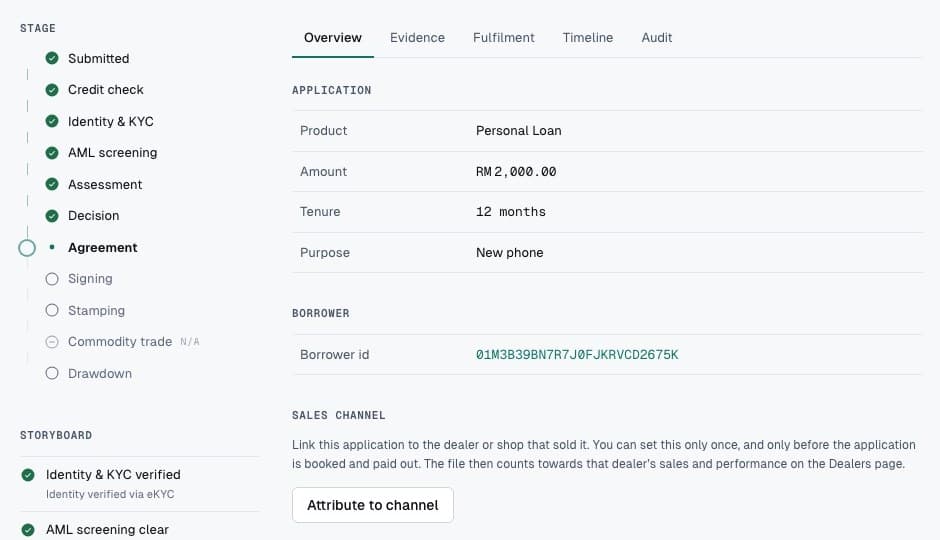
Service, collect and settle to the sen
Repayment schedules, daily accrual and payment allocation run on an append-only ledger. Restructures, top-ups, early settlement and write-offs are recorded against the person who approved them, and collections work by days past due.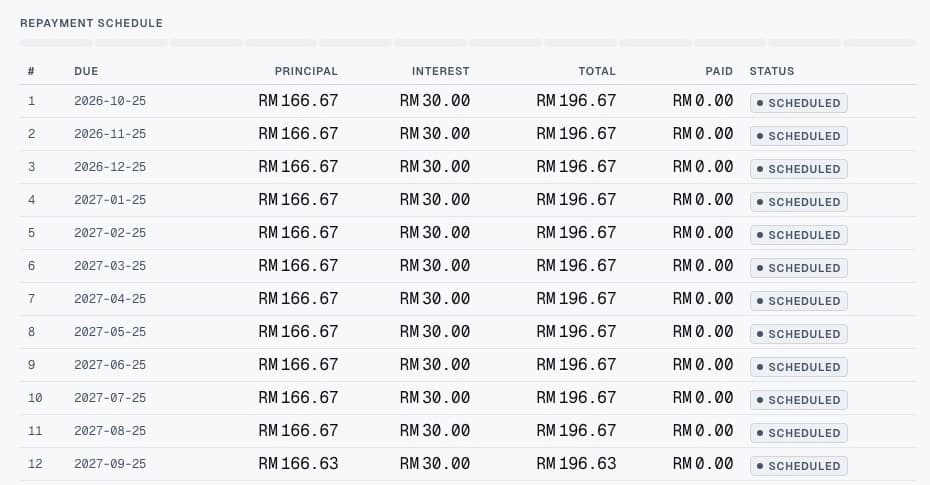
The funding gate: no payout until every check passes
Kenal Loan checks every condition again at the moment of payout, not only when each step finished. If anything has changed since, the money waits and the reason is logged.
Money moves only when:
- The agreement is signed and the signature verified
- The agreement is stamped
- AML, PEP and sanctions screening is clear
- Every required document is present and clean
- The borrower has consented to the payment provider
- For Tawarruq, the commodity trade is complete
For Malaysian moneylenders
Collex is Kenal Loan for KPKT-licensed moneylenders in Malaysia.
Collex puts the Malaysia moneylending pack in front: the rules of the Moneylenders Act 1951 built into pricing, agreements and reporting, so your team works inside the limits by default rather than checking them by hand.
- Rate ceilings checked when a product is published and again at booking
- Simple late charges on the overdue instalment only, never compounded
- Agreements generated in the statutory Bahasa Melayu form
- Payout held until the agreement is signed and stamped
- The KPKT monthly portfolio return, from the same ledger
What you get
One system of record for every loan, from the first click to the closing entry.
A borrower app
Apply, verify, sign and repay on the phone, in English, Bahasa Melayu or Bahasa Indonesia.
A staff console
Origination, decisions, payout, servicing, collections, complaints and reports in one place.
One ledger
An append-only, double-entry ledger that finance, auditors and regulators can all read.
Reports
The KPKT monthly return and management reports, with the conventional and Islamic split.
Capabilities
Product Studio
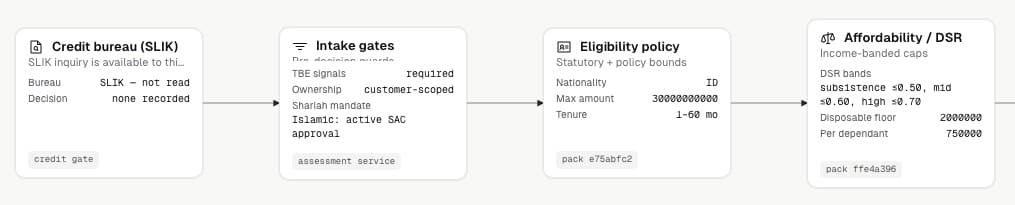
Launch, reprice and reword products without a release. Your team drafts and publishes versioned products with their rate bands, fees, late-charge rules, required documents and repayment shapes, and builds the credit assessment pipeline step by step.
Origination under your credit policy
- Decide first: the credit answer comes before identity checks and document uploads
- Score bands, arrears rules, affordability (DSR) and eligibility rules
- Officer counter for staff-assisted applications
- Company borrowers, collateral and an approved valuer panel
Conventional and Islamic in one system
- Conventional pricing inside statutory caps, flat or reducing balance
- Tawarruq and Murabahah with the commodity trade gate
- Shariah committee approval of products and wording
- A terms guard that keeps conventional words off Islamic screens
Products and channels
- Repayment shapes: equal, step-up, balloon, seasonal, pay-in-4 and fortnightly
- Device financing through dealers, with device checks and dealer settlement
- Bulk reprice of a live conventional book, previewed before it applies
- Your brand and product wording in each language
Servicing, collections and care
- Servicing to the sen: accrual, allocation, restructure, top-up and write-off
- Early settlement with rebate or ibra'
- Collections by days past due, with promises to pay, a watchlist and quiet hours
- A complaints desk with service-level timers
How it fits your stack
Every check in the loan flow is a provider slot. Use Kenal's own products, or connect the bureau, payment and messaging providers you already have.
- Kenal eKYC, Kenal Document and Kenal Stamps connect out of the box
- Credit bureau, payout and request-to-pay, and SMS, email and push through provider slots
- Market packs carry each country's rules, so the core stays the same in every market
- Run it as a managed service, in your own cloud or at your licensed premises
Compliance and security
Controls a regulator can inspect, built into the system rather than added to a process manual.
- Double-entry ledger
- Append-only. Corrections are reversing entries, never edits.
- Chained audit log
- Every state change and staff action is hash-chained and verified on a schedule.
- Access by capability
- Roles built from named permissions, with multi-factor sign-in for staff and device-bound one-time PINs for borrowers.
- Statutory caps
- Rate ceilings and late-charge limits applied by the system, not by memory.
- Screening after payout
- Borrowers are rescreened nightly, with hold, refer and unwind actions if a hit appears.
- Personal data
- Personal data encrypted, with a versioned privacy notice and consent records.
Questions buyers ask
Which loan types does Kenal Loan support?
Kenal Loan supports any loan type you configure, from personal loans and device financing to hire purchase, working capital and asset-backed credit. Conventional loans and Islamic financing run side by side in the same system. Product Studio sets each product's pricing, fees, repayment shape and required documents, so a new product is a configuration change your team publishes, not a software project.
Does Kenal Loan handle Islamic financing such as Tawarruq and Murabahah?
Yes. Kenal Loan runs Tawarruq and Murabahah alongside conventional loans, with Islamic rules built into the process. Payout waits for the commodity trade to complete, late charges follow ta'widh and gharamah without compounding, and ibra' applies at early settlement. Your Shariah committee approves products and wording in the console, and a terms guard keeps conventional words such as interest off Islamic screens.
What is the funding gate?
The funding gate is the rule that no money leaves until every condition passes again at the moment of payout. Kenal Loan rechecks the signature, the stamp, AML screening, the documents, the borrower's payment consent and, for Tawarruq, the commodity trade. If anything has changed since a step was completed, the payout waits, and the reason is recorded for your auditors.
What is Collex?
Collex is Kenal Loan for KPKT-licensed moneylenders in Malaysia. It ships with the Malaysia market pack: Moneylenders Act rate ceilings checked when a product is published and again at booking, simple late charges on the overdue instalment only, agreements in the statutory Bahasa Melayu form, and the KPKT monthly portfolio return produced from the same ledger as every other report.
Can we change products and rates without a software release?
Yes. Product Studio lets your risk and product teams draft, version and publish products themselves. They set rate bands, fees, late-charge rules, early-payment terms, required documents, repayment shapes and your own product wording in each language. Conventional products can be repriced across the live book in one previewed action, and every published version is kept, so you can show exactly which terms applied to each loan.
Does Kenal Loan work in Indonesia as well as Malaysia?
Yes. Kenal Loan uses market packs, so each country's rules, documents, currency and language come from a signed, dated pack rather than custom code. The Malaysia pack covers moneylending and Islamic financing. The Indonesia pack covers multifinance products such as consumer credit, finance leases and Murabahah, and the borrower app runs in English, Bahasa Melayu and Bahasa Indonesia.
How does Kenal Loan connect to identity checks, signing and stamping?
Kenal Loan has a slot for each check in the loan flow and works with the rest of Kenal out of the box. Kenal eKYC verifies the borrower, Kenal Document reads bank statements and Kenal Stamps handles LHDN stamp duty. Kenal Sign, now in development, will tie the signature to the verified identity. Your existing bureau, payment and messaging providers connect through the same provider slots.
Used with
Kenal Loan has a slot for each of these in the loan flow, so the borrower's verified identity carries through.
See Kenal Loan with your products
Tell us what you lend and where. We will walk you through the borrower app and console configured for your products and market.